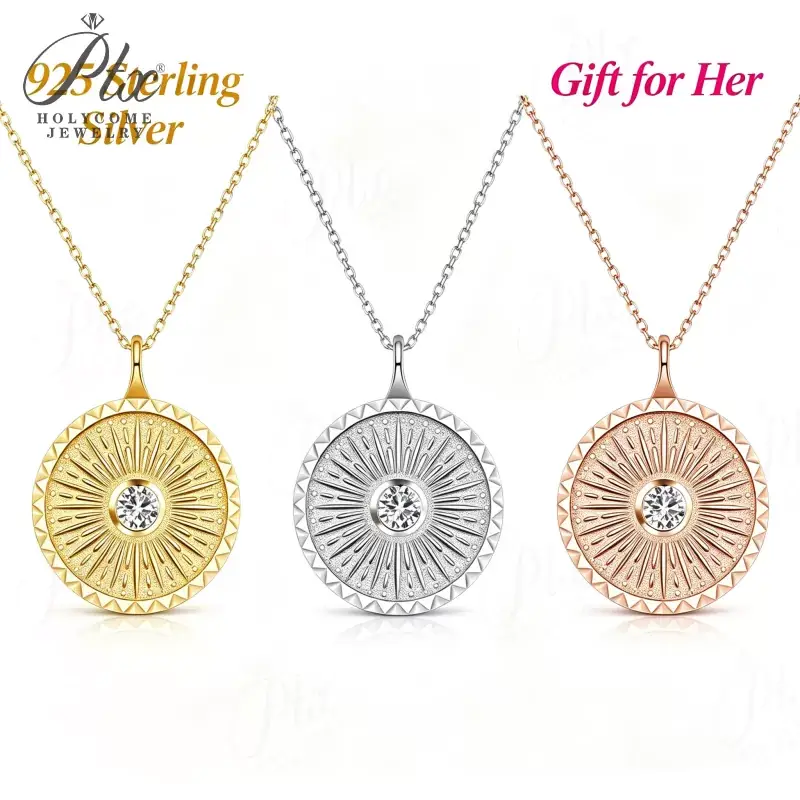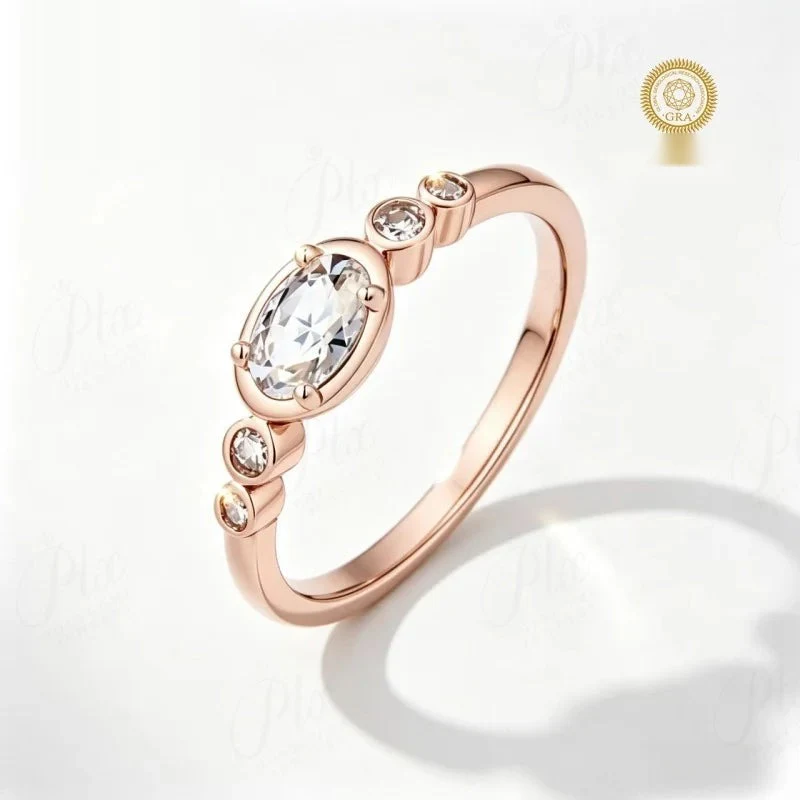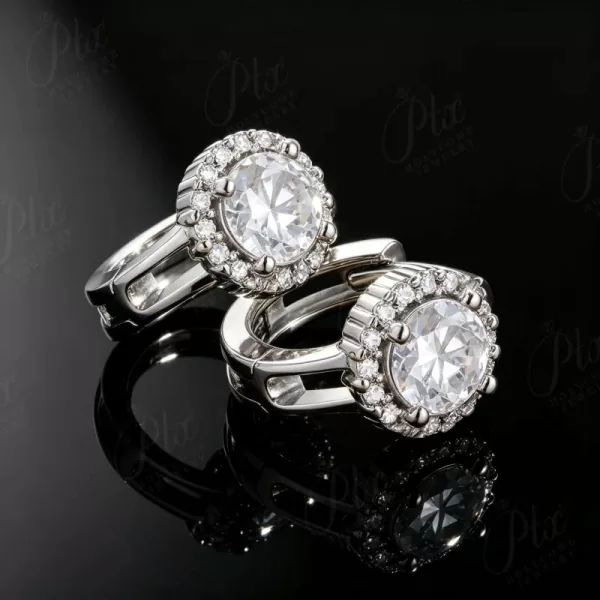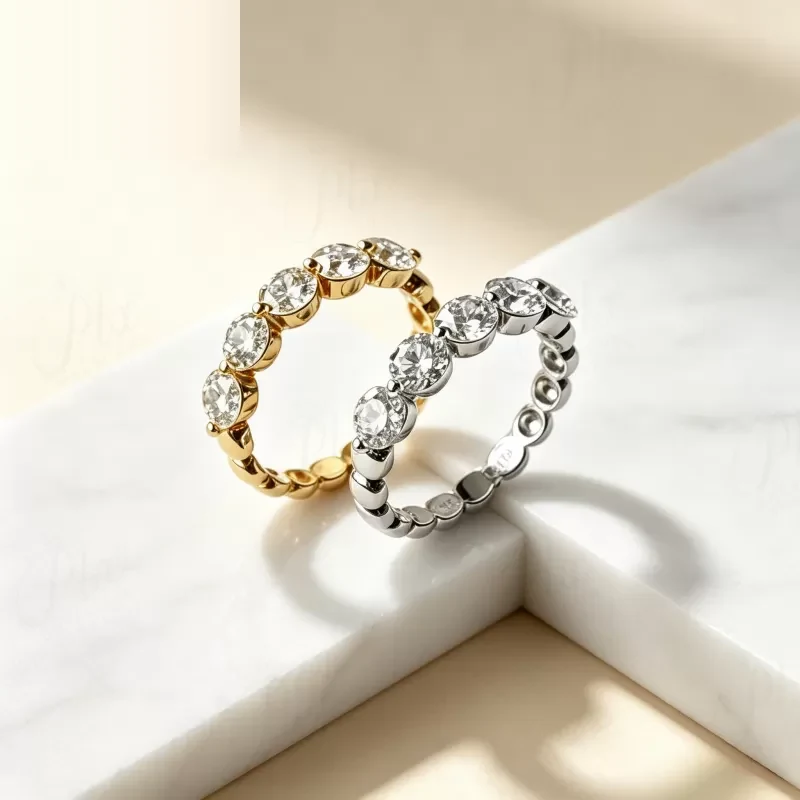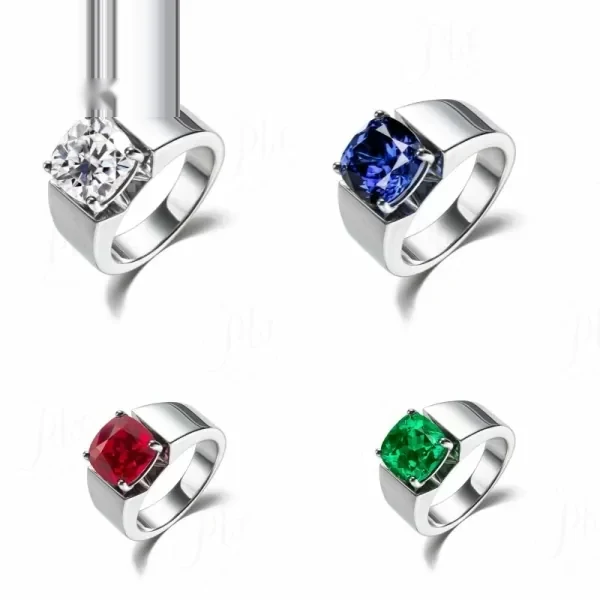
A retailer in Stockholm insured a twenty-piece shipment at full diamond replacement value. When one ring was lost in transit, the insurer declined: the appraisal listed diamond, 1.2 carat, on a sterling silver band. Moissanite is not diamond, and the paperwork had to say so. The claim sat for three months before the retailer updated the appraisal and re-filed.
Insurance for moissanite jewelry fails on paperwork, not on the stone. Below is the documentation buyers need for transit insurance and for the end client's retail rider.
Why moissanite needs its own appraisal language
Moissanite is silicon carbide, not diamond and not a lab-grown diamond. Appraisals that list moissanite as diamond get rejected. We issue a moissanite appraisal note with each piece that lists the stone as moissanite, the dimensions in millimetres, the carat equivalent and the metal fineness. The note matches the stamp on the piece. Buyers who insure against diamond replacement value will be under-paid on a claim, because the replacement cost of moissanite is a fraction of diamond.
What the appraisal should list
We list stone type (moissanite), shape, dimensions (e.g. 6.5 mm round), carat equivalent, color grade, clarity grade, metal fineness (925, 14K, 18K), total weight in grams and retail replacement value. The value is the buyer's landed cost plus a margin, not a diamond price list number. We reference the material on Wikipedia lab-grown diamond entry when explaining to buyers why moissanite is valued separately; it is a different material with a different price curve.
Scheduled personal property and riders
End clients insure moissanite rings under a scheduled personal property rider on a home or renter's policy. The rider requires an appraisal, a photo and a receipt. Buyers should hand the client the appraisal note and the receipt in one sealed envelope. Without the appraisal, the rider cannot be written. We include the appraisal note in the shipping pack at no extra charge; buyers can add a branded appraisal card at USD 1.50 per piece.
Shipping insurance versus retail insurance
Shipping insurance covers loss in transit from our bench to the buyer. We ship every parcel by express courier, insured for the full invoice value, at our cost. The buyer's retail insurance covers loss after delivery. The two are separate. Buyers should not assume the transit policy covers a ring lost in the store; it does not. Our shipment insurance guide lists the courier and the coverage value we ship under.
Replacement cost versus retail value
Insurers pay replacement cost, not retail value. A ring retailed at $300 has a replacement cost of about $120 to $150 at our bench. Buyers should set the insured value at the replacement cost they would pay us to re-make the piece, not at the retail price. Over-insuring inflates the premium; under-insuring means the client cannot replace the ring after a loss. Our QC and spec sheet guide lists the weights and values we put on the appraisal so buyers can reconcile them. Our payment and deposit guide shows the invoice value used for transit insurance.
What to do when a claim is filed
When a client files a claim, the insurer asks for three things: the appraisal, the receipt and a photo of the piece. Buyers should hand both the appraisal and the receipt to the client at the point of sale, in one sealed envelope. If the piece is lost, the insurer pays the replacement cost listed on the appraisal. If the piece is damaged, the insurer pays the repair cost, which we quote at about USD 25 per prong and USD 12 per re-plating. We re-issue the appraisal on request for USD 5 per piece, so buyers keep a copy on file.
We refresh the appraisal value every two years on request, because moissanite pricing and alloy costs move. Buyers should send the original appraisal number and the new replacement cost; we re-issue the note within 2 working days. Without a refresh, the insured value lags the replacement cost by about 10 to 15 percent, which is enough to leave a client under-covered after a loss. We flag the two-year refresh cycle on every shipping pack.
Do insurers cover moissanite?
Yes, under a scheduled personal property rider. The appraisal must list the stone as moissanite, not diamond. Appraisals that list moissanite as diamond get rejected.
What paperwork do buyers get with each piece?
A moissanite appraisal note with dimensions, carat equivalent, metal fineness and retail replacement value, plus the fineness stamp certificate. Branded appraisal cards are available at USD 1.50 per piece.
Is transit insurance included?
Yes. Every parcel ships by express courier, insured for the full invoice value, at our cost. The coverage runs from our bench to the buyer's receiving address.
Can a buyer upgrade coverage later?
Yes, on the next order. We adjust the appraisal value and add a branded card. The transit policy is per shipment, so there is no annual renewal to track.
Send us the piece count and retail value band. We return an appraisal template, a fineness certificate pack and the transit insurance coverage note with your order. Ask us to set up documentation for your next moissanite shipment.
Frequently Asked Questions
Is moissanite a good diamond alternative for retail buyers?
Yes for price-sensitive customers who want brilliance and hardness. Moissanite ranks 9.25 on the Mohs scale, holds up to daily wear and costs a fraction of a natural diamond of the same size, so it resells fast in bridal and fashion lines.
What is the minimum order for wholesale moissanite?
MOQ starts at 50 pieces per design for stock items. Custom cuts and private-label settings usually start at 100–300 pieces depending on the mold.
Do you provide certificates with moissanite stones?
Yes. Every parcel ships with GRA or IGI documentation listing carat weight, color grade and cut. We recommend passing the certificate to your end customer for trust.
How long does sample and bulk production take?
Samples ship in 3–5 days. Bulk runs take 15–20 days under 500 pieces, and 25–30 days for custom work.